
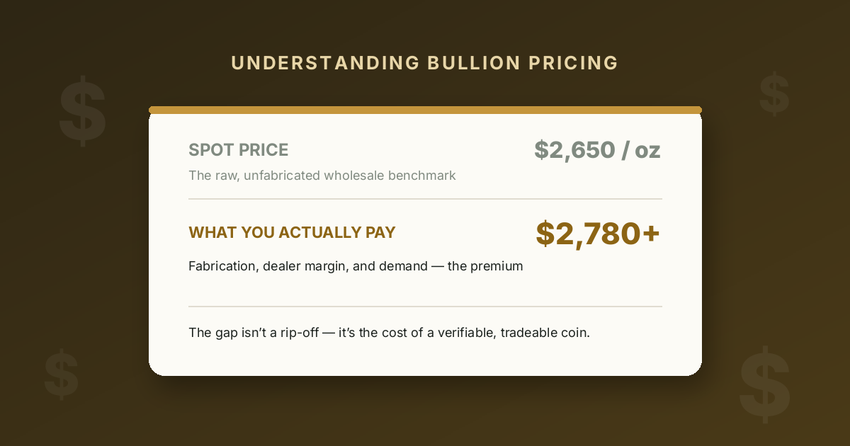
If you've started shopping for your first gold or silver coin, you've probably had this moment: you check the spot price online, then look at what a dealer actually wants for the coin, and the numbers don't match. Not even close, sometimes. Your first thought might be that you're being overcharged. The truth is more nuanced — and understanding it is one of the most useful things a beginner can learn before spending real money on physical metal.
What "Spot Price" Actually Means
Spot price is the current market price for one troy ounce of raw, unfabricated metal — think of it as the wholesale price of the raw material itself. It updates constantly during trading hours based on global supply and demand. But you can't buy "spot price gold" the way you'd buy a stock at the quoted price. Spot price is a benchmark, not a retail price tag. Nobody — not a mint, not a dealer, not a pawn shop — sells finished coins or bars at that number, because turning raw metal into something you can hold, verify, and trust costs money.
Where the Premium Comes From
The difference between spot price and what you actually pay is called the premium, and it isn't arbitrary markup. A few things typically make it up: fabrication costs (someone has to refine, strike, and finish the metal into a coin or bar), dealer overhead and margin (bullion dealers carry inventory, insure it, and need to make a living like any retailer), and distribution (metal moves from refiner to wholesaler to dealer to you, and each step adds a small cost).
Supply and Demand for That Specific Product
This is the part beginners often miss — premiums aren't fixed. When a lot of people want to buy at once (often during economic uncertainty), premiums on popular coins can spike even while the underlying spot price stays flat, simply because dealers can't restock fast enough. A well-known coin like an American Eagle or Canadian Maple Leaf usually carries a higher, steadier premium than generic rounds or bars, precisely because recognizability makes it easier to resell later. Whether that brand premium is worth paying is its own question, covered in Silver Eagles vs. generic silver rounds.
How to Calculate the Premium Yourself
You don't need a dealer to tell you the premium. You need two numbers and one line of math:
Premium % = (all-in price − spot price × ounces of pure metal) ÷ (spot price × ounces of pure metal)
Use the pure metal content, not the coin's total weight. Some gold coins are alloyed with copper or silver for durability, so a "one-ounce" coin can weigh more than an ounce while containing exactly one ounce of gold. The product listing or mint specification will say.
Here's an example with made-up but realistic-looking numbers. Say gold spot is $4,000 an ounce and you're comparing three one-ounce gold products:
- Government-minted coin at $4,200: $200 over spot, so $200 ÷ $4,000 = 5%.
- Generic one-ounce bar at $4,120: $120 over spot, or 3%.
- The same government coin at a second dealer for $4,360: $360 over spot, or 9%.
Silver works the same way but the percentages run higher. If silver spot is $50, a popular government silver coin at $56 carries a $6 premium, or 12%, while a generic round at $52.50 is 5%.
Now add the fees that don't show up in the headline price. Pay for that $4,200 coin with a credit card at a dealer that adds 3% for card payments and you pay another $126, so the real premium is $326, or about 8%. Add $25 shipping and you're near 9%, the same as the dealer who looked expensive.
What Counts as a "Fair" Premium
There's no single right number, but there are reasonable ranges depending on the product: widely recognized government-minted coins typically run somewhat higher than generic bars or rounds of the same metal and weight, and silver generally carries a higher percentage premium than gold because fabrication costs matter more relative to a lower per-ounce metal value. The way to actually judge fairness isn't memorizing a target percentage — it's comparing prices across a few reputable dealers for the exact same product. If one dealer's premium is dramatically higher than several others for the identical coin, that's your signal, not some fixed rule of thumb.
A Practical Way to Shop
Before buying, check the live spot price, then compare the all-in price (including any listed shipping or card-processing fees) across at least two or three established dealers for the same specific product. Paying a bit more for a well-known, easily resellable coin is often worth it; paying a dramatically inflated premium for an obscure product is not.
Check Your Invoice Against the Spot Price at Lock-In
Most online dealers lock your price when you place the order, not when you pay or when it ships. That gives you a clean way to check your purchase afterward:
- Note the spot price at the moment you order. Screenshot it or write it down along with the time.
- Run the premium math on your invoice. Use the total you actually paid, including shipping, insurance, and any payment surcharge, divided by the ounces of pure metal. The result should land near the premium you compared across dealers. If it's several points higher, look for a fee you missed.
- Ask for the buyback price on the same product. Most dealers publish what they'll pay to buy it back. The gap between what you paid and that bid is your true round-trip cost, and it's often bigger than the premium alone. Here's how the buyback spread works.
- Keep the invoice. Your total cost, premium included, is your cost basis when you eventually sell.
Premium Mistakes That Cost Beginners the Most
- Comparing the price to spot at a different time. Spot moves all day. Comparing a dealer's price to a spot quote from yesterday can make a fair premium look outrageous, or an inflated one look fair.
- Ignoring how you pay. Card surcharges and shipping can add several percentage points. Compare the checkout total, not the listed price.
- Paying a collector premium for bullion. Words like “proof,” “limited mintage,” or “graded” can push a markup from single digits to many times that, and you rarely get it back when you sell. Here's the word that turns a 5% markup into a 60% one.
- Chasing the lowest premium from an unknown seller. A price well below every established dealer is a classic counterfeit warning sign. Read why a fake gold bar can pass the ring test before buying from a marketplace listing.
- Assuming the premium comes back when you sell. A dealer's buyback price sits well below its selling price for the same coin, so much of the premium you paid is a cost, not a stored value. Check the dealer's published buy price before you assume otherwise.
Spot price will always be the headline number you see — but it was never the number you were going to pay. Understanding the premium, and what actually drives it, turns confusing sticker shock into an informed purchase decision.