
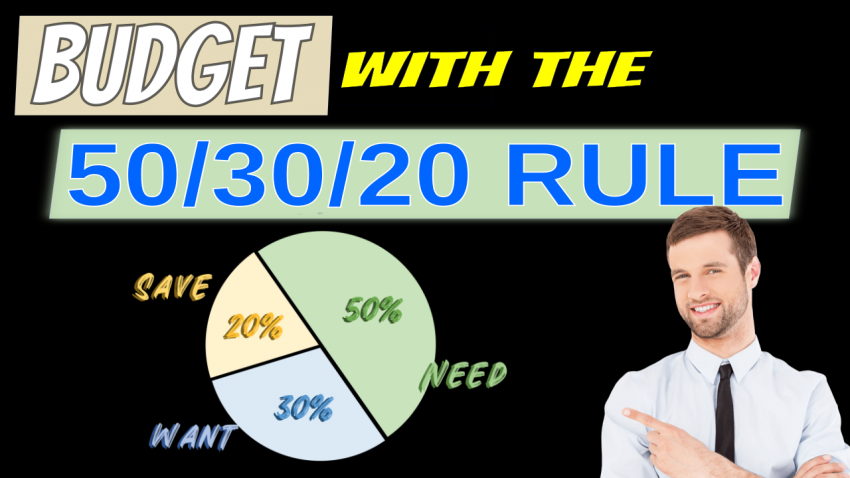
The 50/30/20 rule sounds simple until you try it. Half for needs, 30% for wants, 20% for savings. Then you look at your paycheck and the questions start. Is that 50% of your salary or what hits your account? Does your 401(k) count? Is your credit card payment a need or savings? And what if rent alone is 40% of your pay?
That last one is where a lot of people decide the rule doesn't work for them. It still can. You just need to apply it to your real numbers and know how to adjust when they don't fit.
The rule, briefly
The 50/30/20 rule was popularized by Elizabeth Warren and her daughter Amelia Warren Tyagi in their 2005 book All Your Worth. It splits after-tax income into three buckets, as Morningstar's summary lays out: 50% for needs, 30% for wants, and 20% for savings and debt repayment.
That's it. You don't track twenty categories, just three totals. This page assumes you've already picked 50/30/20 and want to make it work on your actual pay.
Step one: find the right base number
Use your take-home pay, the amount deposited into your account. Our guide to reading your paycheck shows where that is on your pay stub.
One adjustment is worth making. If your employer takes a 401(k) contribution out before your pay is deposited, that money is savings you've already done. Many people add it back to their take-home number and count it toward the 20%. Otherwise, the rule pushes you to save 20% on top of what's already going to retirement, which may be more than you need, or makes your savings look smaller than it is.
Step two: sort debt into the right bucket
This is the most common point of confusion. A widely used reading of the rule, explained in this breakdown from Achieve, is:
- Minimum payments are needs. You have to make them, like rent.
- Anything above the minimum goes in the 20%. Extra payments shrink debt and future interest, so they work like savings.
So the 20% bucket is shared. You decide how to split it between your emergency fund, retirement, and extra debt payments. If you're carrying high-interest card debt, choosing between the debt avalanche and snowball shows which balance should get the extra money first.
A worked example where the numbers don't fit
The figures below are a made-up example. Alex gets $3,400 deposited each month. Another $200 goes to a 401(k) before deposit. Adding that back gives a base of $3,600.
The targets:
- Needs (50%): $3,600 × 0.50 = $1,800
- Wants (30%): $3,600 × 0.30 = $1,080
- Savings and extra debt (20%): $3,600 × 0.20 = $720
Now Alex's actual needs:
- Rent: $1,450
- Utilities: $150
- Groceries: $400
- Car insurance: $110
- Gas: $140
- Phone: $50
- Student loan minimum: $190
- Credit card minimum: $60
Total needs: $2,550. That's $2,550 ÷ $3,600 = about 71% of the base, or $750 over the 50% target. Rent alone is $1,450 ÷ $3,600, about 40%.
That's not unusual. The Department of Housing and Urban Development considers households that pay more than 30% of their income for housing to be cost-burdened, and in many cities, ordinary rents push well past that before you've bought a single grocery.
What to do when needs blow past 50%
You have two jobs here: build a split you can live with this month, and work the needs number down over time.
This month: borrow from wants, protect savings. The 30% wants bucket is the cushion. Alex's working split looks like this:
- Needs: $2,550 (about 71%)
- Wants: $450 (12.5%)
- Savings: $600 (about 17%), which is the $200 401(k) plus $400 more
Check: $2,550 + $450 + $600 = $3,600. It's not 50/30/20, but every dollar is accounted for, and savings stays close to target. Keep savings above zero even if it's not 20%. A smaller automatic transfer beats none, especially while your first emergency fund is still small.
Over the next six to twelve months: shrink the needs. Rent is the biggest lever, but you may not be able to move until your lease ends. Meanwhile, go after the smaller fixed bills. Calling to negotiate or shopping your internet, phone, and insurance bills can trim the needs bucket without moving. Every $50 a month you cut there is $600 a year that can go back to wants or savings. When the lease comes up, use your 50/30/20 math to set a rent ceiling for the next place.
Watch what counts as a need. Groceries are a need. Takeout isn't. A basic phone plan is a need; the unlimited premium tier is partly a want. Being strict about the line keeps the needs bucket from swelling.
How to check your split each month
You only need three totals, so this takes about ten minutes.
At the end of the month, add up everything you paid for needs and everything for wants from your bank and card statements. Divide each by your base number. Then open your savings and retirement accounts and confirm that the deposits actually landed.
If it worked, your needs and wants percentages are close to the split you planned (not necessarily 50/30, but your adjusted version), and the savings total matches your target. If wants ran over, look at which purchases pushed it there; that's usually two or three categories, not everything. Recheck whenever your pay or rent changes, since both shift every percentage.
Mistakes that make 50/30/20 fail
- Calculating from gross salary. 50% of a $60,000 salary is a lot more than 50% of what you take home. Use the deposit amount.
- Counting minimum payments as savings. It makes your savings look healthy while your actual savings balance doesn't grow. Minimums are needs.
- Calling every want a need. If dining out, streaming bundles, and the newer car all land in needs, the rule stops telling you anything.
- Quitting because the numbers don't match. The percentages are a target, not a pass-fail test. A 65/15/20 split you track is far more useful than a 50/30/20 split you abandon in week two.
- Saving whatever's left at the end of the month. Usually that's nothing. Automate the savings transfer for payday so it happens first.
The rule's real value isn't the exact percentages. It's a quick, honest snapshot of whether your fixed costs leave room to save. If they don't, now you know exactly how far off you are and which bucket has to give.
Check us out on 📺 You Tube 📺
Check out our Media Section: 📺 Media 📺
The 50/30/20 Rule on a Real Paycheck (Even When Rent Eats Half)
Discover more from Grow Beyond Green
Subscribe to get the latest posts sent to your email.